Social Events & Meetings
Managing Lock Up - By SPONSOR PKF Francis Clark LLP
Managing Lock Up - By SPONSOR PKF Francis Clark LLP
FINANCIAL MANAGEMENT - MANAGING LOCK UP
Lock up within a law firm is an essential area in which a practice needs to maintain control to assist in generating cash resources and as part of maintaining their overall financial stability requirements.
What is lock up?
Lock up represents a working capital requirement in a law firm. This is derived from both office balances outstanding and unbilled amounts of time recorded in undertaking a matter to be charged to clients. In essence these are assets / resources due to the practice which will potentially be converted to cash over a period of time.
Office balances outstanding include amounts billed to your clients for fees and disbursements but also for disbursements in which the practice has funded but remain unbilled and not settled from funds held on account in the interim
Unbilled time is often referred to as accrued income or work in progress (WIP) and for lock up purposes should reflect the time recorded at the fee earner’s full charge out rate.
Why is managing lock up important?
In simplistic terms to demonstrate how lock up affects cash resources; a practice will undertake a matter where it may not be possible to bill the client for a lengthy period of time. Over this time frame the law firm will be incurring various related operating costs which are in turn being reflected in the underlying unbilled time generated as the matter progresses.
The operating costs need to be financed from the practice over the course of the matter but no cash is actually received from the client until the unbilled time is converted to a bill of cost and settled. Hence there is a time frame where outgoing cash exceeds incoming cash.
Multiply this scenario by several hundreds of matters and the absolute level of the interim cash requirement can soon become a significant amount. To finance this requirement, funding needs to be obtained which can be from sources such as a bank loan or overdraft and from the business owners’ personal cash resources which would be introduced into the business as capital.
Whilst banks may look to provide an element of funding towards working capital requirements this will only be up to a certain limit and it is the principals of a law firm that are required to provide the majority of this cash requirement.
Where lock up can be efficiently managed, the cash call from the principals own resources and the bank / financing costs can also be kept at a minimum which can be a strong incentive.
The extent of the cash needed from lock up will vary from practice to practice dependent on size, structure, work types undertaken and its internal policies and procedures, which are where the firm’s COFA can play an important role.
How can firms manage and improve lock up?
Initially to measure how efficient the firm is in managing lock up, key performance indicators (KPIs) can be used. The main ones are debtor days and WIP days which can be benchmarked against industry data. High results of these KPIs can indicate a potential issue within lock up which needs to be addressed.
In terms of the ongoing management of lock up there are a number of routine areas that firms can review, introduce or improve internal policies. The extent of policies and procedures adopted will of course vary dependent on the size of practice, work types undertaken etc., however example areas which can be considered are shown below.
Unbilled Time
-
An important starting point is to ensure a firm and its fee earners can, and do, record their time promptly. Clearly being able to manage lock up within unbilled time can only be effective if it is appropriately recorded in the first instance.
-
Certain time recording systems can produce exception reports to show which fee earners do not regularly keep their time recording up to date, and this can be addressed accordingly.
-
Where a tendency arises in firms not to time record for fixed fees it should be emphasised this is still vitally important, not only for managing underlying lock up to assess the cash resource requirement but also in assessing if such matters are profitable and sustainable.
-
Unbilled time reports, which where possible should be produced on an aged profile basis, should be regularly reviewed (at least monthly) and circulated to the appropriate fee earners to assess billing potential or non-recoverable amounts requiring action.
-
Highlighting to fee earners the risk that the older the unbilled time the increased chance arises of its value diminishing or becoming non recoverable.
-
A policy of ensuring non recoverable unbilled time is removed from system on a timely basis is important as any overstatement of unbilled time could provide a false sense of security on future income / cash inflow.
-
Where permitted and practical, have an interim billing policy over a course of a client matter communicated to clients at the outset.
-
Some practice systems can set unbilled time or outstanding costs limits which can highlight when these are exceeded. This is of benefit for assessing interim billing requirements or having a policy of stopping work at that point.
-
Changing billing patterns so that unbilled income is converted into bills which are not solely issued at the month end will have its benefit in avoiding peaks and troughs within the working capital requirement. ( In practice this can be a challenging behavioural pattern to break!)
Outstanding unbilled disbursements / billed costs
-
For disbursements and costs, wherever possible clients should be requested to make an upfront payment into the client bank account to cover these. General disbursements paid or incurred represent office money which can potentially be settled from any payments held on account.
-
For firms that do not have a separate credit control department, internal procedures need to be clear on who is responsible for chasing outstanding costs, i.e. is it the fee earners, cashiers department, etc.
-
As with unbilled time, regular reports showing outstanding costs preferably on an aged profile basis should be circulated to the fee earners responsible to monitor outstanding balances and take action as necessary.
-
Having fee earner incentive schemes based on cash collection rather than billing to encourage recovery.
In practice, managing lockup to improve the working capital position can at times be challenging not only in changing behavioural patterns in a practice, but also in balancing client relationships.
The above hopefully gives some practical areas which can be considered or provides some comfort to firms that they already have robust systems within this important area.
This publication is produced by Francis Clark LLP for information only and is not intended to constitute professional advice. Specific professional advice should be obtained before acting on any of the information contained herein. Whilst Francis Clark LLP is confident of the accuracy of the information in this publication (as at the date of its production), no duty of care is assumed to any direct or indirect recipient of this publication and no liability is accepted for any omission or inaccuracy.
Like Back to Top Seen 942 times Liked 0 times
Subscribe to Updates
If you enjoyed this, why not subscribe to free email updates and join over 1295 subscribers today!
Subscribe to updates
Alternatively, you can subscribe via RSS 
All email subscriptions must be confirmed to comply with GDPR.
Related Posts
06th September 2017 | September 2016

News from the Devon & Somerset Junior Lawyers' Division Devon and Somerset Junior Lawyer's Division – 2016 AGM and elections The Devon and Somerset JLD is many things – a networking group, a voice for junior lawyers in the region and a contributor to change. We bring young lawyers in the region together. We host events introducing junior lawyers to their counterparts in other professions. And we take the opinions of our members to the national JLD to be put to the Law Society, the SRA and the Ministry of Justice on a range of issues. This year, one of our key areas for development has been diversity. We are keen to carry this through to the elections, and so we are having our biggest push to a range of junior lawyers from Devon and Somerset represented on the 2016/2017 Committee. We would like to invite anyone who falls into our membership criteria* who would like to be involved in the Devon and Somerset JLD to run for election at our AGM on Thursday 10 November 2016. All positions are voluntary and can be held alongside a busy professional day-job: we all understand that work sometimes has to come first, and everyone will pitch in to keep the workload down. The following positions will be up for election: Chair Provide support and leadership to all members of the team and liaise with DASLS. The Chair will lead the Committee's meetings and manage the challenges of working with a group of lawyers! Vice Chair The main point of contact for sponsors of the JLD, the Vice Chair helps to steer projects and events. The Vice Chair will maintain existing relationships with supporters and sponsors and help to find and foster new ones. Treasurer Controlling the finances of the Committee and balancing sponsorship, membership fees and ticket prices to ensure our members get best value. This role requires fiscal responsibility! General Secretary Keeping the Committee on track by updating the membership records and liaising with law firms in the region. Helping the Committee to stay efficient and on-message, with reference to our Constitution. Communications Get the message out! Anyone who is good at communicating is suitable for this role – being able to use a range of communication methods is a bonus. Social Secretary This is a shared role, with two people working side by side to arrange our busy social calendar and arrange high-quality networking events, and our popular summer ball. Sports Representative Team sports are a great way to build connections and friendships, and the Sports Secretary is tasked with arranging fun and inclusive events, including our highly competitive rounders match with the as-yet unbeaten DASLS. Charities Representative The Charities rep will be responsible for putting forward nominations for our charity of the year and raising funds throughout the year. Education Representative The JLD has a proud tradition of putting on junior-lawyer specific seminars and training sessions. The education representative will liaise with our partners to provide current, useful events to help improve the skills and knowledge of our members. National Representative Get involved with the legal sector, liaising with the national Committee, responding to consultations and feeding key information about the sector to our members. Travel to The Law Society in London once a quarter to provide a voice for Devon and Somerset junior lawyers. Diversity Representative Helping to provide support to all members of the JLD, keeping the diversity policy current and ensuring that all of our members are treated equally. Somerset Representative The committee has been largely based in Exeter and the surrounding area, but in recent years we have committed time and resources to growing our Somerset presence. As the Somerset rep, you will continue that work and organise Somerset-based events. For more information about any role, or to re...
06th September 2017 | September 2016
Are YOU the weakest link? by SPONSOR - Alchemy Cyber security is a hot topic at the moment. Hardly surprising since we are seeing both a significant increase in the number of cyber attacks and an increase in the level of sophistication of how such attacks are perpetrated. Fortunately firms are slowly starting to wake up to the realities: that they could be a target and that they need to urgently become cyber resilient. Law firms are especially vulnerable to cyber attacks since they hold large amounts of highly sensitive client data, yet few firms have a clear strategy to prevent attacks and mitigate their impacts. Even fewer have briefed their staff on the types of cyber attacks that could occur and how to avoid them. People are a firm’s greatest asset but also the weakest links in its security strategy. It only takes one click on a malicious link in a phishing email to jeopardise a firm’s security and the security of its client data. One ill-advised click is all it takes to put a firm out of action for hours or even for days. Several law firms have been the victims of attacks during the past year however most keep silent about it. Whilst commercially understandable, this means their staff have less incentive to stay informed and take steps to avoid cyber attacks. They may even become complacent and think cyber attacks happen to other firms and not to theirs. YOU could be your firm’s weakest link - whether you’re a senior partner or an unpaid intern. Do YOU know the answer to any of these questions? Does your firm have a clear strategy to prevent cyber attacks? Do you know what that strategy is? Are you regularly informed about the types of cyber attacks that are prevalent and how to avoid them? Have you been advised on how to maintain cyber security? Do you know how resilient your firm is to cyber attacks? Can you recognise the symptoms of a cyber attack? Becoming cyber resilient The best way for a firm to become cyber resilient is to implement a multi-layered approach: perform mock phishing attacks; have regular updates to software, firewalling, email cleansing, threat detection processes and management; back up files on a regular basis and store them off-site. However, since the weakest link will be the people working for a firm it’s essential to train them well and often, keep them informed and regularly monitor their compliance with security policies. What should a security policy include? These are just a few of the things a staff security policy should require: use strong passwords and change them regularly password protect all devices back-up data throughout the day shred all documents exercise care on incoming phone calls be cautious what you share on social media sites never open suspicious links in email, tweets, posts, online ads, messages or attachments – even if you think you know the source stay observant and immediately report anything suspicious or if anything unusual happens on your computer or laptop Don’t be the weakest link in your firm! Take steps to be cyber resilient! Alchemy Systems have 19 years of IT systems experience and are a Microsoft Partner. Alchemy Systems Designs, Supplies, Installs, Supports and Protects clients’ IT systems. The legal sector has always been a strategic focus. Our staff are experienced in the specific needs and challenges of law firms from service desk to strategy to protection services. Tel. 0330-043-080198 email. sales@alchemysys.co.uk www.alchemysouthwest.co.uk...
06th September 2017 | September 2016
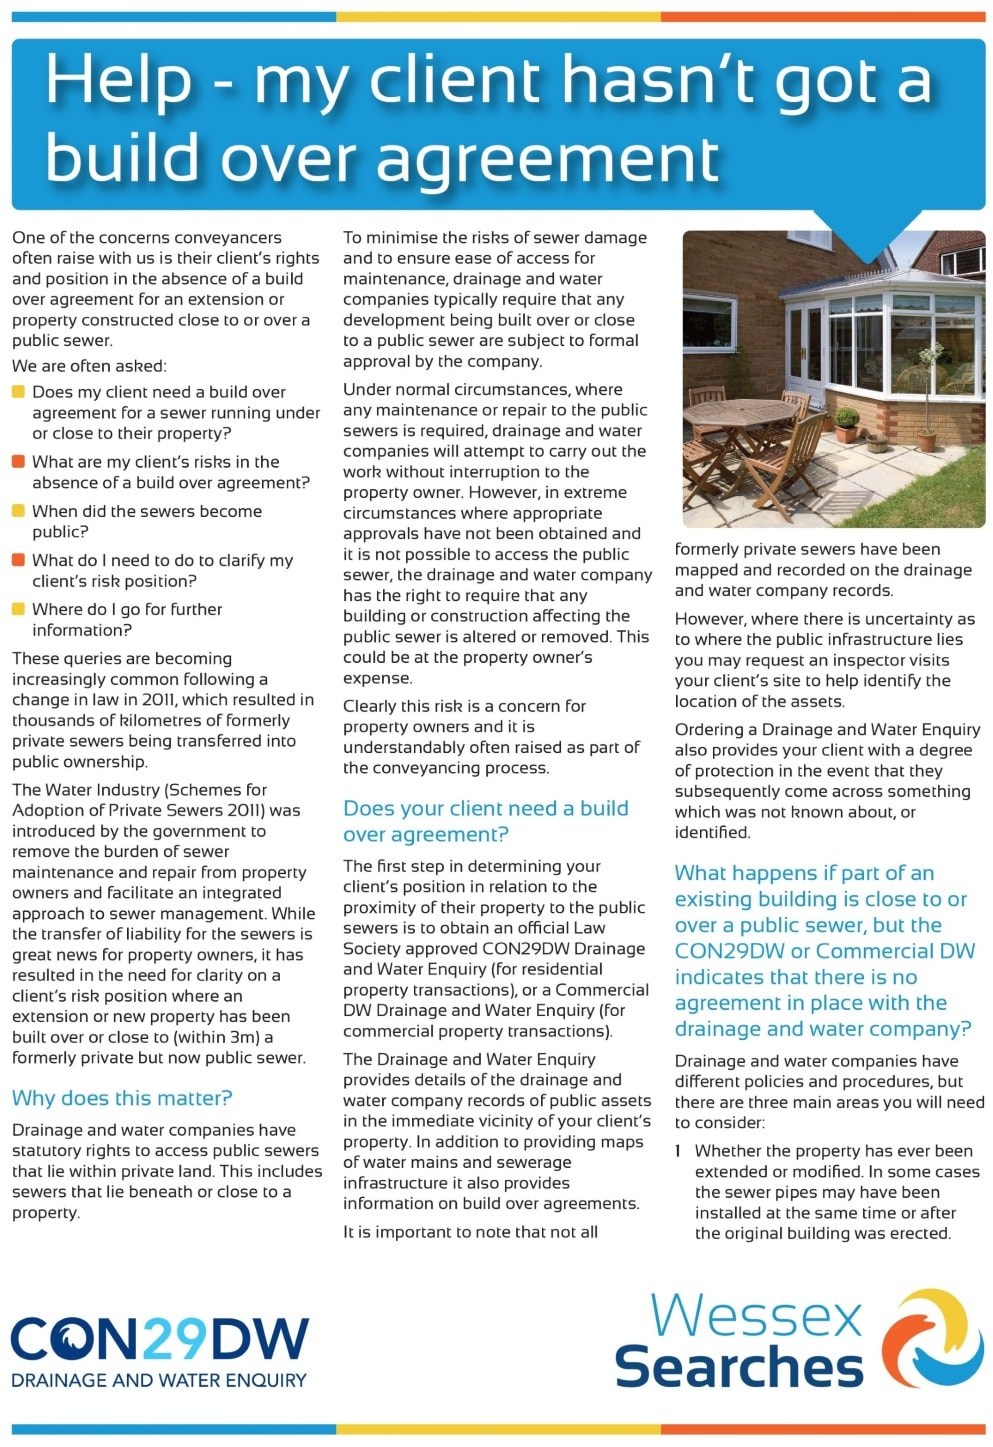
Build over agreement by SPONSOR Wessex Searches ...
06th March 2020 | March 2020

Dear All, This year really is flying by. I have just had my birthday. After updating you previously on the excellent catch up I had with the Law Society CEO Paul Tennant on his visit to the south west last November, I had not expected to be back in touch with him quite so soon. Sadly, this time it was in less happy circumstances. I was, like many of you, shocked and saddened in January to hear the news and see the pictures of the substantial fire at Chancery Lane in London. I have emailed Paul Tennant and James Shepherd, our Law Society Relationship Management Executive, to send our best wishes and we are hoping that the building will be back to full use very soon. As I write this report, preparations are in full swing for the 2020 DASLS Legal Awards & Dinner. As you know the Annual Dinner is being held again this year at Exeter Cathedral. The event is to take place on the 30th April 2020. After the success of last year, we are hoping that once again the event is sold out which would mean we will have around 480 people attending. If you have not done so already, please contact Llew Nicholls and the team at our Awards partners ‘Grow Marketing’ who have worked very hard alongside our very own Tony and Monique to achieve full sponsorship of this event. You can contact Llew to book the remaining places by emailing Llew directly at Llew@growmarketinguk.com. There have been more nominations than ever before with more entries making the short list. Please do not miss this dazzling occasion. You will all have received DASLS latest 2020 training courses programme. Tony Steiner and the team have worked hard to arrange these events. You will see that as members you get preferential rates and if appropriate reduced rates for multiple attendees from your firms. Please take advantage of these services as a proportion of the monies do go to support our Society’s broad continuing education offering. If I do not see you individually before I look forward to catching up with you at the 2020 DASLS Legal Awards and Annual Dinner in April. With very best wishes Nigel Lyons President 2019-2020...
06th March 2020 | March 2020

New AML Regulations and the pursuit of the beneficial owner. Introduction The new Money Laundering & Terrorist Finance (Amendment) Regulations 2019 which came into force on 10 January have modified a number of aspects of the 2017 AML Regulations, with which we have been complying for some time. However, many firms’ procedures hark back to the earlier days of the 2007 Regulations and have not been modified or updated much over recent years. This article seeks to set out what the new Regulations in fact require, and the steps we should be taking in relevant cases. The Policy It has been true for some time that the ultimate aim of all the regulatory rules is transparency – it has always been the case that the use of artificial structures such as trusts, companies, bearer shares, foundations and charities – whilst perfectly legal – have to some extent also benefitted from the extra anonymity they offer to the true owner and recipient of the funds and services we provide. If we offer services to these types of entity, the Regulations require us to go some way to identifying the individuals who are actually benefitting from our services, and this entails uncovering the true ownership of the organisation. Whilst this would be difficult in many instances – Cayman Island companies with bearer shares, for example – we must nevertheless attempt to get some assurances from the creators of the companies, accountants or registrars as to the ownership of the shares, and have some way of being notified of any change in ownership. We also need to be aware of the PEP and Sanctions status of these individuals. Further, for UK companies, the PSC Regulations 2016 impose an exactly similar obligation on the companies themselves to identify their beneficial owners and notify Companies House of any shareholder with 25% or more of the shares or exercising control over management of the business. The Regulations The Regulations provide that we must, as part of our CDD procedures Identify the client – this means coming to know who they are, by name and some other characteristic, e.g. address, date of birth, date of incorporation Verify that identity – by means of reliable and independent data and documentation Identify the beneficial owner (if the client is an entity) – though not necessarily verifying that identity Identify and verify the identity of the person actually instructing us (if not already done). What this means for us When acting for a COMPANY (that is not a listed company) the Regulations require us to obtain Details of the company as registered (which must be proven by a copy of the register entries available from Companies House or equivalent registry) – name, number, registered office address, principal place of business the law to which it is subject details of its governing documentation (its memorandum) names of the directors. Names of any beneficial owners, and the identity of any individual owners of legal entities which own the client Names and verification of the persons instructing us on behalf of the company, and their authority to do so. Note that we cannot rely on the information provided by the company under the PSC Regulations but we must undertake our own research in order to fulfil our CDD duties. Further, if as part of that research, we discover that the Companies House data on PSC’s is incorrect, then we are now under a further obligation to notify the Registrar of Companies of this fact. We also need to establish that PEPs and Sanctions checks are also undertaken. If genuinely positive entries are revealed in response we should undertake enhanced CDD steps or cease to act, accordingly. Electronic searches are a permissible avenue to use provided the search provider can offer us the necessary assurances that the person actually claiming an identity is IN FACT that person. Check also whether ...