Social Events & Meetings
Merger-mania by SPONSOR Barclays
Merger-mania by SPONSOR Barclays
Merger-mania: the truth behind the trends
As law firms face increased competition, pressure to lower fees and wider economic uncertainty, Andrea Delay, Head of Professional Services at Barclays, explores the potential behind the growing trend for consolidation and mergers.
The re-emergence of the legal community’s ‘mega-merger’ – in the form of the three-way tie-up between CMS, Nabarro and Olswang – has served to refocus attention on consolidation in a competitive sector facing downward pressure on fee income.
But in reality, despite these occasional unions, the legal landscape has not changed too dramatically in the past decade or so – notwithstanding the arrival in England and Wales of the ABS newcomers, the Alternative Business Structures that came in under the Legal Services Act of 2007.
However, anecdotal evidence suggests many firms across the sector are currently involved in merger discussions.
The market drivers
As Brexit and the political and economic changes in the US and Europe unfold over the coming months and years, ‘uncertainty’ remains the watchword. This has made it very difficult for a number of law firms to forecast and budget. But for the fleet of foot, opportunity knocks.
Many larger firms are either looking to expand their existing international reach or are considering building out an overseas presence and will turn a merger to their advantage. This, I believe, stems from the need to better service clients, where the trend, demonstrated by Barclays’ own procurement of legal services, is to achieve greater efficiency and focus on improving relationships.
In this context, a merger can help maintain a firm’s position. Not only does it remove one competitor, it can also provide economies of scale. Perhaps most importantly though, it facilitates the filling of any geographic or service gaps.
A warning
The obvious caveat in all this is that mergers are complex, time-consuming and expensive undertakings, not all of which are successful. Many opportunities in the current landscape which would be considered low-hanging fruit have already been taken, leaving some of the more challenging options.
If they do go the course, there will likely be a duplication of property (a long lease held by one firm may even sink a deal) and personnel. There will also be systems and processes to integrate, along with client management.
So, while an immediate post-merger increase in fee income is to be expected, it is unlikely that there will be a commensurate rise in profit. In the UK legal sector, PwC has shown in its Law Firms Survey 2016 that fee income per chargeable hour has seen an average decrease of 4.0% reported by the top 51-100 firms1.
UK profit margins were down by up to 1.4% across the top 100. Deteriorating net profit margins have, according to PwC, “been driven by higher staff costs, either as a result of increased headcount or increases to base salaries”. This is against a backdrop of lower than average utilisation, increasing margin pressure and an aggressive ‘more-for-less’ mentality on the part of the client – none of which are going away any time soon.
New money
It may not just be coincidence, then, that as the price of re-energising a firm post-merger becomes clearer, some £500m of external investment – mostly private equity – has been injected into the legal sector. In 2015, LegalWeekreported that commercial law firm Gateley became the first UK practice to go public, raising more than £30m as it listed on London Stock Exchange’s AIM2. That being said, although there is increasing appetite for PE firms to invest in the legal sector, I believe IPOs will remain few and far between as the need is rare for such large sums to be raised, even when investing to grow and compete.
Partnering for success
The bank’s role in the legal sector is built on relationships, mutual trust and understanding. Service provision ranges from everyday transaction banking and funding of partner capital, working capital lines and fixed asset spends, to a business advisory and funding capacity in the merger process. As law firm mergers are cashless, the funding typically covers the realisation of synergies between the two firms.
The UK banking market is competitive for partner capital and working capital funding. Incoming PE money is all about putting in equity whereas banking is a debt play. However, PE investment will change the structure of the law firm and, as banks, we will need to adapt and review, on a case-by-case basis, our debt offering. To do so we will work to understand the strategy and drivers of the investor and how the firm will take this forward.
Responding to change
I believe that cost pressures are set to continue as clients seek greater savings, and the general economy remains fragile. There will be further commoditisation of certain services such as conveyancing and will-writing too as technology comes to the fore.
Further market consolidation is the likely response. As this gathers pace, the gap between the progressive and the resolutely traditional will widen and success may hinge on the wise selection of bedfellows.

The views expressed in this article are the views of the author alone and do not necessarily reflect the views of the Barclays Bank PLC Group nor should they be taken as statements of policy or intent of the Barclays Bank PLC Group. The Barclays Bank PLC Group takes no responsibility for the veracity of information contained in the third party guides or articles and no warranties or undertakings of any kind, whether express or implied, regarding the accuracy or completeness of the information given. The Barclays Bank PLC Group takes no liability for the impact of any decisions made based on information contained and views expressed. Barclays is a trading name of Barclays Bank PLC and its subsidiaries. Barclays Bank PLC is authorised by the Prudential Regulation Authority and regulated by the Financial Conduct Authority and the Prudential Regulation Authority (Financial Services Register No 122702). Registered in England. Registered number is 1026167 with registered office at 1 Churchill Place, London E14 5HP. December 2016.
+ Please note: this is a mobile phone number and calls will be charged in accordance with your mobile tariff.
Like Back to Top Seen 606 times Liked 0 times
Subscribe to Updates
If you enjoyed this, why not subscribe to free email updates and join over 1292 subscribers today!
Subscribe to updates
Alternatively, you can subscribe via RSS 
All email subscriptions must be confirmed to comply with GDPR.
Related Posts
05th September 2017 | March 2017

LawCare - Keeping Fit in a Sedentary Job Keeping Fit in a Sedentary Job Physical inactivity currently costs the NHS in England around £1.8 billion per year, and around £8.3 billion to the wider economy in sick days and premature deaths 1. For lawyers working long hours in a job which essentially involves sitting at a desk all day, being active and keeping fit can be a challenge. Walking is one of the easiest ways to meet your physical activity recommendations; it’s cheap, requires no special equipment, and has a low risk of injury. Walking regularly at any speed can help to manage weight, boost the immune system and even reduce the risk of some cancers as well as osteoporosis. Brisk walking has even more benefits, including lowering blood pressure, improving heart and lung health, and raising mood. The rise in popularity of wearable fitness trackers means that there’s probably someone in your workplace who is trying to get in their recommended 10,000 steps per day (including 250 per hour). Even if that’s not you, walking as much as possible throughout the day isn’t as difficult as you might imagine. The standard advice to take the stairs not the lift, and get off the bus/tube/tram a stop early or park further away has been oft-repeated, but once you’re at your desk, how can you factor those extra steps into your day? Always volunteer for the coffee run. Then collect up the dirty cups afterwards and take them to the kitchen. Set your default printer to one on a different floor. Drink plenty of water (which has its own health benefits), and use a toilet on the other side of the building. Stand up and walk around when on the phone. Not only will it help with your step count, but standing when you speak can make you sound more confident and authoritative. Go for a walk in your lunch break. Make the most of your fitness tracker. Many prompt you to move each hour. If yours doesn’t or you don’t have one, set an alarm on Google or an app to remind you to get up and move or stretch every hour. Put the waste-paper bin on the opposite side of the room. When meeting with local clients, colleagues, or others, offer to go to them rather than have them come to your office. Go to speak to colleagues in person, rather than emailing or phoning. Encourage others at your workplace to get involved, leading lunchtime walks, holding walking meetings, or an after work running club (ensure it will suit beginners). Even if you can’t walk about, standing is better than sitting, so if there’s any aspect of your work you could do standing up, do. Adjustable desks are available which convert from sitting to standing height. Walking 250 steps (recommended per hour by some fitness trackers) takes less than three minutes, so if all else fails, simply get up and pace. Don’t let a sedentary job mean your health suffers. With just a few changes you could meet your fitness goals even at work. 1 Statistics from the 'Economic costs of physical inactivity' report published by the British Heart Foundation LawCare 0800 279 6888 www.lawcare.org.uk ...
05th September 2017 | March 2017

News from the Devon & Somerset Junior Lawyers' Division This month's article has been written by the JLD's National Representative, Georgia Wookey.As National Representative of the Devon and Somerset JLD, I provide a voice to our members at National JLD level by meeting my counterparts from JLDs across England and Wales at the Law Society, London, three times a year. We last met at the end of January 2017 and as expected at the top of the agenda for discussion was the SRA's proposal for the introduction of the solicitors qualifying exam (SQE). 6 January marked the close of the SRA's second consultation into the introduction of the SQE and I understand that there may be a third consultation on its way later this year. The JLD encourage everyone to take part and respond either as firms or as individuals as the introduction of the SQE will mark a huge change to entry in to the legal profession. Should you wish to see the full consultation paper please visit https://www.sra.org.uk/sra/consultations/solicitors-qualifying-examination.page In general, the JLD is supportive of the idea of a centralised solicitors qualifying exam regulated by the SRA - at present each academic provider delivers its own program for the LPC which means there is variation and no consistency in the academic stage of training undertaken by current trainee solicitors. However there are a few concerns and suggestions which the JLD raises in its response to the consultation, three of which are:- 1) Work experience element - , the JLD would like to see a minimum of two years 'work experience' which should be split across no more than four separate placements, comparative to the current training contract system. The time spent in each placement should be of a sufficient standard to actually equip junior lawyers with the necessary legal skills for when they qualify as solicitors and not merely give them 'the opportunity' to gain legal skills. 2) Preparatory study - the SRA provides no information at present as to the likely cost of any preparatory training course to be taken ahead of sitting any SQE exams. It is also concerning that there is the suggestion that there will be no need to attend such a course as "would-be" junior lawyers could have the option to study without the course, giving rise to the possibility of a two tier system whereby some junior lawyers will have paid to study a course, whilst others have taken the self-study route potentially disadvantaging those from lower socio-economic backgrounds as a result. 3) Implementation date - the proposed implementation date of the new SQE route is August 2019. This start date is considered to be too soon and does not give firms or academic providers the chance to change their systems and courses in readiness for the new system. This is particularly concerning as some firms have already started to recruit their 2019 trainee solicitors. Universities are already working on their 2019 course content and some current undergraduates will be graduating in 2019, causing uncertainty for them. I have only highlighted three of the points raised by the JLD. To see the full JLD response, please visit http://communities.lawsociety.org.uk/junior-lawyers/policy/sra-a-new-route-to-qualification-the-solicitors-qualifying-exam-sqe/5060068.article If you have any comments or concerns you'd wish to raise with Devon and Somerset JLD in relation to the SQE please do contact us on dsjld17@gmail.com. We will keep you posted on any further developments as we become aware of them....
05th September 2017 | March 2017

President's Charity - Thanks for amazing support THANKS FOR AMAZING SUPPORT THROUGHOUT CHARITABLE PARTNERSHIP North Devon Hospice has been named as charity of the year for the Devon & Somerset Law Society, as nominated by President Mark Roome. We are coming to the end of a fantastic year-long partnership between North Devon Hospice and the Devon and Somerset Law Society. Society President, Mark Roome, chose the hospice as his charity of the year having seen at close quarters just what a different their care makes to local patients and families, all of whom are affected by life-limiting illnesses such as cancer. Chief Executive of North Devon Hospice, Stephen Roberts, thanked members of DASLS for their tremendous support throughout the year. “This has been a very fruitful partnership, where some really fun opportunities have been taken up by members, and in turn, vital funds have been raised for the hospice. We’ve seen Society members get down and dirty by taking part in our Mission:Unbreakable commando challenge event, and also donate generously at the annual Somerset dinner. It was an honour to attend this year and speak to you all about how your support allows us to care for local people going through the toughest of times.” Mark Roome said of the charity of the year partnership, “I’m very proud of the way that members of DASLS have taken this cause to their hearts and shown such generous support. North Devon Hospice is very dear to me, being based in the same town as my own practice. The care they provide is absolutely second to none, and there are few families in this area who have not been touched by their loving support down the years. It has been a pleasure to have the hospice as my charity of the year, and my thanks go out to all members who have shown such fantastic support.” Stephen Roberts added, that to mark the end of the partnership, there was one more notable fundraising activity happening… 10,000ft up in the air! “On Friday 10th March, we are holding a special DASLS Skydive event at Honiton airfield, where several brave folk will be doing a sponsored parachute jump in aid of North Devon Hospice. President Mark Roome has already signed up, alongside many other colleagues, and it’s not too late to join them! Once again, our immense thanks go to all who have supported North Devon Hospice throughout the last 12 months. It has helped us provide even more care to local people. For example, we have doubled our Hospice to Home team in the last year. They care for patients round the clock in their own homes when symptoms become more severe, but this kind of service development is only possible thanks to local generosity, just like we’ve seen from the Devon and Somerset Law Society.” To find out more about the DASLS skydive day on Friday 10th March, please contact the Fundraising Team at North Devon Hospice: Tel: 01271 344248 Email: clairesherwood@northdevonhospice.org.uk ...
05th September 2017 | March 2017
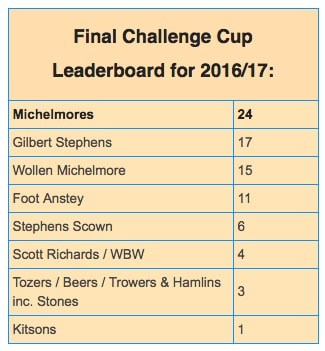
Challenge Cup 2016/17 - and the winner is .... Congratulations to Michelmores Solicitors who have won the Devon & Somerset Law Society Challenge Cup for 2016/17. The DASLS Challenge Cup is a fun tournament of six competitive events held over a twelve month period commencing March of each year. Law Firms or other groups of DASLS members may enter as many events as they choose, and different people may enter each event, depending on individual preferences. This year teams have enjoyed events including Skittles, Footgolf, 5-a-Side Football, Pitch & Putt Golf, Ten Pin Bowling and a Quiz Night. The Challenge Cup was presented at the Society's Annual Dinner & Legal Awards at Sandy Park, Exeter on 2nd March 2017. Challenge Cup Quiz Night Report - well done Wollen Michelmore For those who like their general knowledge tested you can’t beat a good old fashioned Pub Quiz. DASLS Annual Challenge Cup Quiz on 26th January 2017 saw entrants agonise over which London landmark was designed so that it could act, albeit unsuccessfully as a giant telescope and from which country did different Coca Cola bottles originate from. In the end it was the collective brains of Wollen Michelmore that took the title of DASLS Challenge Cup Quiz Champions 2017 – prestige that money can’t buy! Congratulations also to Gilbert Stephens in second and WBW in third. Everyone seemed to enjoy themselves, even if they didn’t know you sit in a Sulky when Harness Racing or that Megadeth were the trash metal band that released the album Dystopia. In fairness most didn’t actually know what trash metal is but did know that flamingos derived their colour from their diet of brine shrimp. Thanks go to the Globe at Topsham which proved, once again, to be an excellent venue and to all the teams that entered and helped us raise £58 for DASLS President’s Charity; The North Devon Hospice. ...
06th March 2020 | March 2020

Dear All, This year really is flying by. I have just had my birthday. After updating you previously on the excellent catch up I had with the Law Society CEO Paul Tennant on his visit to the south west last November, I had not expected to be back in touch with him quite so soon. Sadly, this time it was in less happy circumstances. I was, like many of you, shocked and saddened in January to hear the news and see the pictures of the substantial fire at Chancery Lane in London. I have emailed Paul Tennant and James Shepherd, our Law Society Relationship Management Executive, to send our best wishes and we are hoping that the building will be back to full use very soon. As I write this report, preparations are in full swing for the 2020 DASLS Legal Awards & Dinner. As you know the Annual Dinner is being held again this year at Exeter Cathedral. The event is to take place on the 30th April 2020. After the success of last year, we are hoping that once again the event is sold out which would mean we will have around 480 people attending. If you have not done so already, please contact Llew Nicholls and the team at our Awards partners ‘Grow Marketing’ who have worked very hard alongside our very own Tony and Monique to achieve full sponsorship of this event. You can contact Llew to book the remaining places by emailing Llew directly at Llew@growmarketinguk.com. There have been more nominations than ever before with more entries making the short list. Please do not miss this dazzling occasion. You will all have received DASLS latest 2020 training courses programme. Tony Steiner and the team have worked hard to arrange these events. You will see that as members you get preferential rates and if appropriate reduced rates for multiple attendees from your firms. Please take advantage of these services as a proportion of the monies do go to support our Society’s broad continuing education offering. If I do not see you individually before I look forward to catching up with you at the 2020 DASLS Legal Awards and Annual Dinner in April. With very best wishes Nigel Lyons President 2019-2020...
06th March 2020 | March 2020

New AML Regulations and the pursuit of the beneficial owner. Introduction The new Money Laundering & Terrorist Finance (Amendment) Regulations 2019 which came into force on 10 January have modified a number of aspects of the 2017 AML Regulations, with which we have been complying for some time. However, many firms’ procedures hark back to the earlier days of the 2007 Regulations and have not been modified or updated much over recent years. This article seeks to set out what the new Regulations in fact require, and the steps we should be taking in relevant cases. The Policy It has been true for some time that the ultimate aim of all the regulatory rules is transparency – it has always been the case that the use of artificial structures such as trusts, companies, bearer shares, foundations and charities – whilst perfectly legal – have to some extent also benefitted from the extra anonymity they offer to the true owner and recipient of the funds and services we provide. If we offer services to these types of entity, the Regulations require us to go some way to identifying the individuals who are actually benefitting from our services, and this entails uncovering the true ownership of the organisation. Whilst this would be difficult in many instances – Cayman Island companies with bearer shares, for example – we must nevertheless attempt to get some assurances from the creators of the companies, accountants or registrars as to the ownership of the shares, and have some way of being notified of any change in ownership. We also need to be aware of the PEP and Sanctions status of these individuals. Further, for UK companies, the PSC Regulations 2016 impose an exactly similar obligation on the companies themselves to identify their beneficial owners and notify Companies House of any shareholder with 25% or more of the shares or exercising control over management of the business. The Regulations The Regulations provide that we must, as part of our CDD procedures Identify the client – this means coming to know who they are, by name and some other characteristic, e.g. address, date of birth, date of incorporation Verify that identity – by means of reliable and independent data and documentation Identify the beneficial owner (if the client is an entity) – though not necessarily verifying that identity Identify and verify the identity of the person actually instructing us (if not already done). What this means for us When acting for a COMPANY (that is not a listed company) the Regulations require us to obtain Details of the company as registered (which must be proven by a copy of the register entries available from Companies House or equivalent registry) – name, number, registered office address, principal place of business the law to which it is subject details of its governing documentation (its memorandum) names of the directors. Names of any beneficial owners, and the identity of any individual owners of legal entities which own the client Names and verification of the persons instructing us on behalf of the company, and their authority to do so. Note that we cannot rely on the information provided by the company under the PSC Regulations but we must undertake our own research in order to fulfil our CDD duties. Further, if as part of that research, we discover that the Companies House data on PSC’s is incorrect, then we are now under a further obligation to notify the Registrar of Companies of this fact. We also need to establish that PEPs and Sanctions checks are also undertaken. If genuinely positive entries are revealed in response we should undertake enhanced CDD steps or cease to act, accordingly. Electronic searches are a permissible avenue to use provided the search provider can offer us the necessary assurances that the person actually claiming an identity is IN FACT that person. Check also whether ...